
Don't Wait until December - 2026 Tax Planning Edition
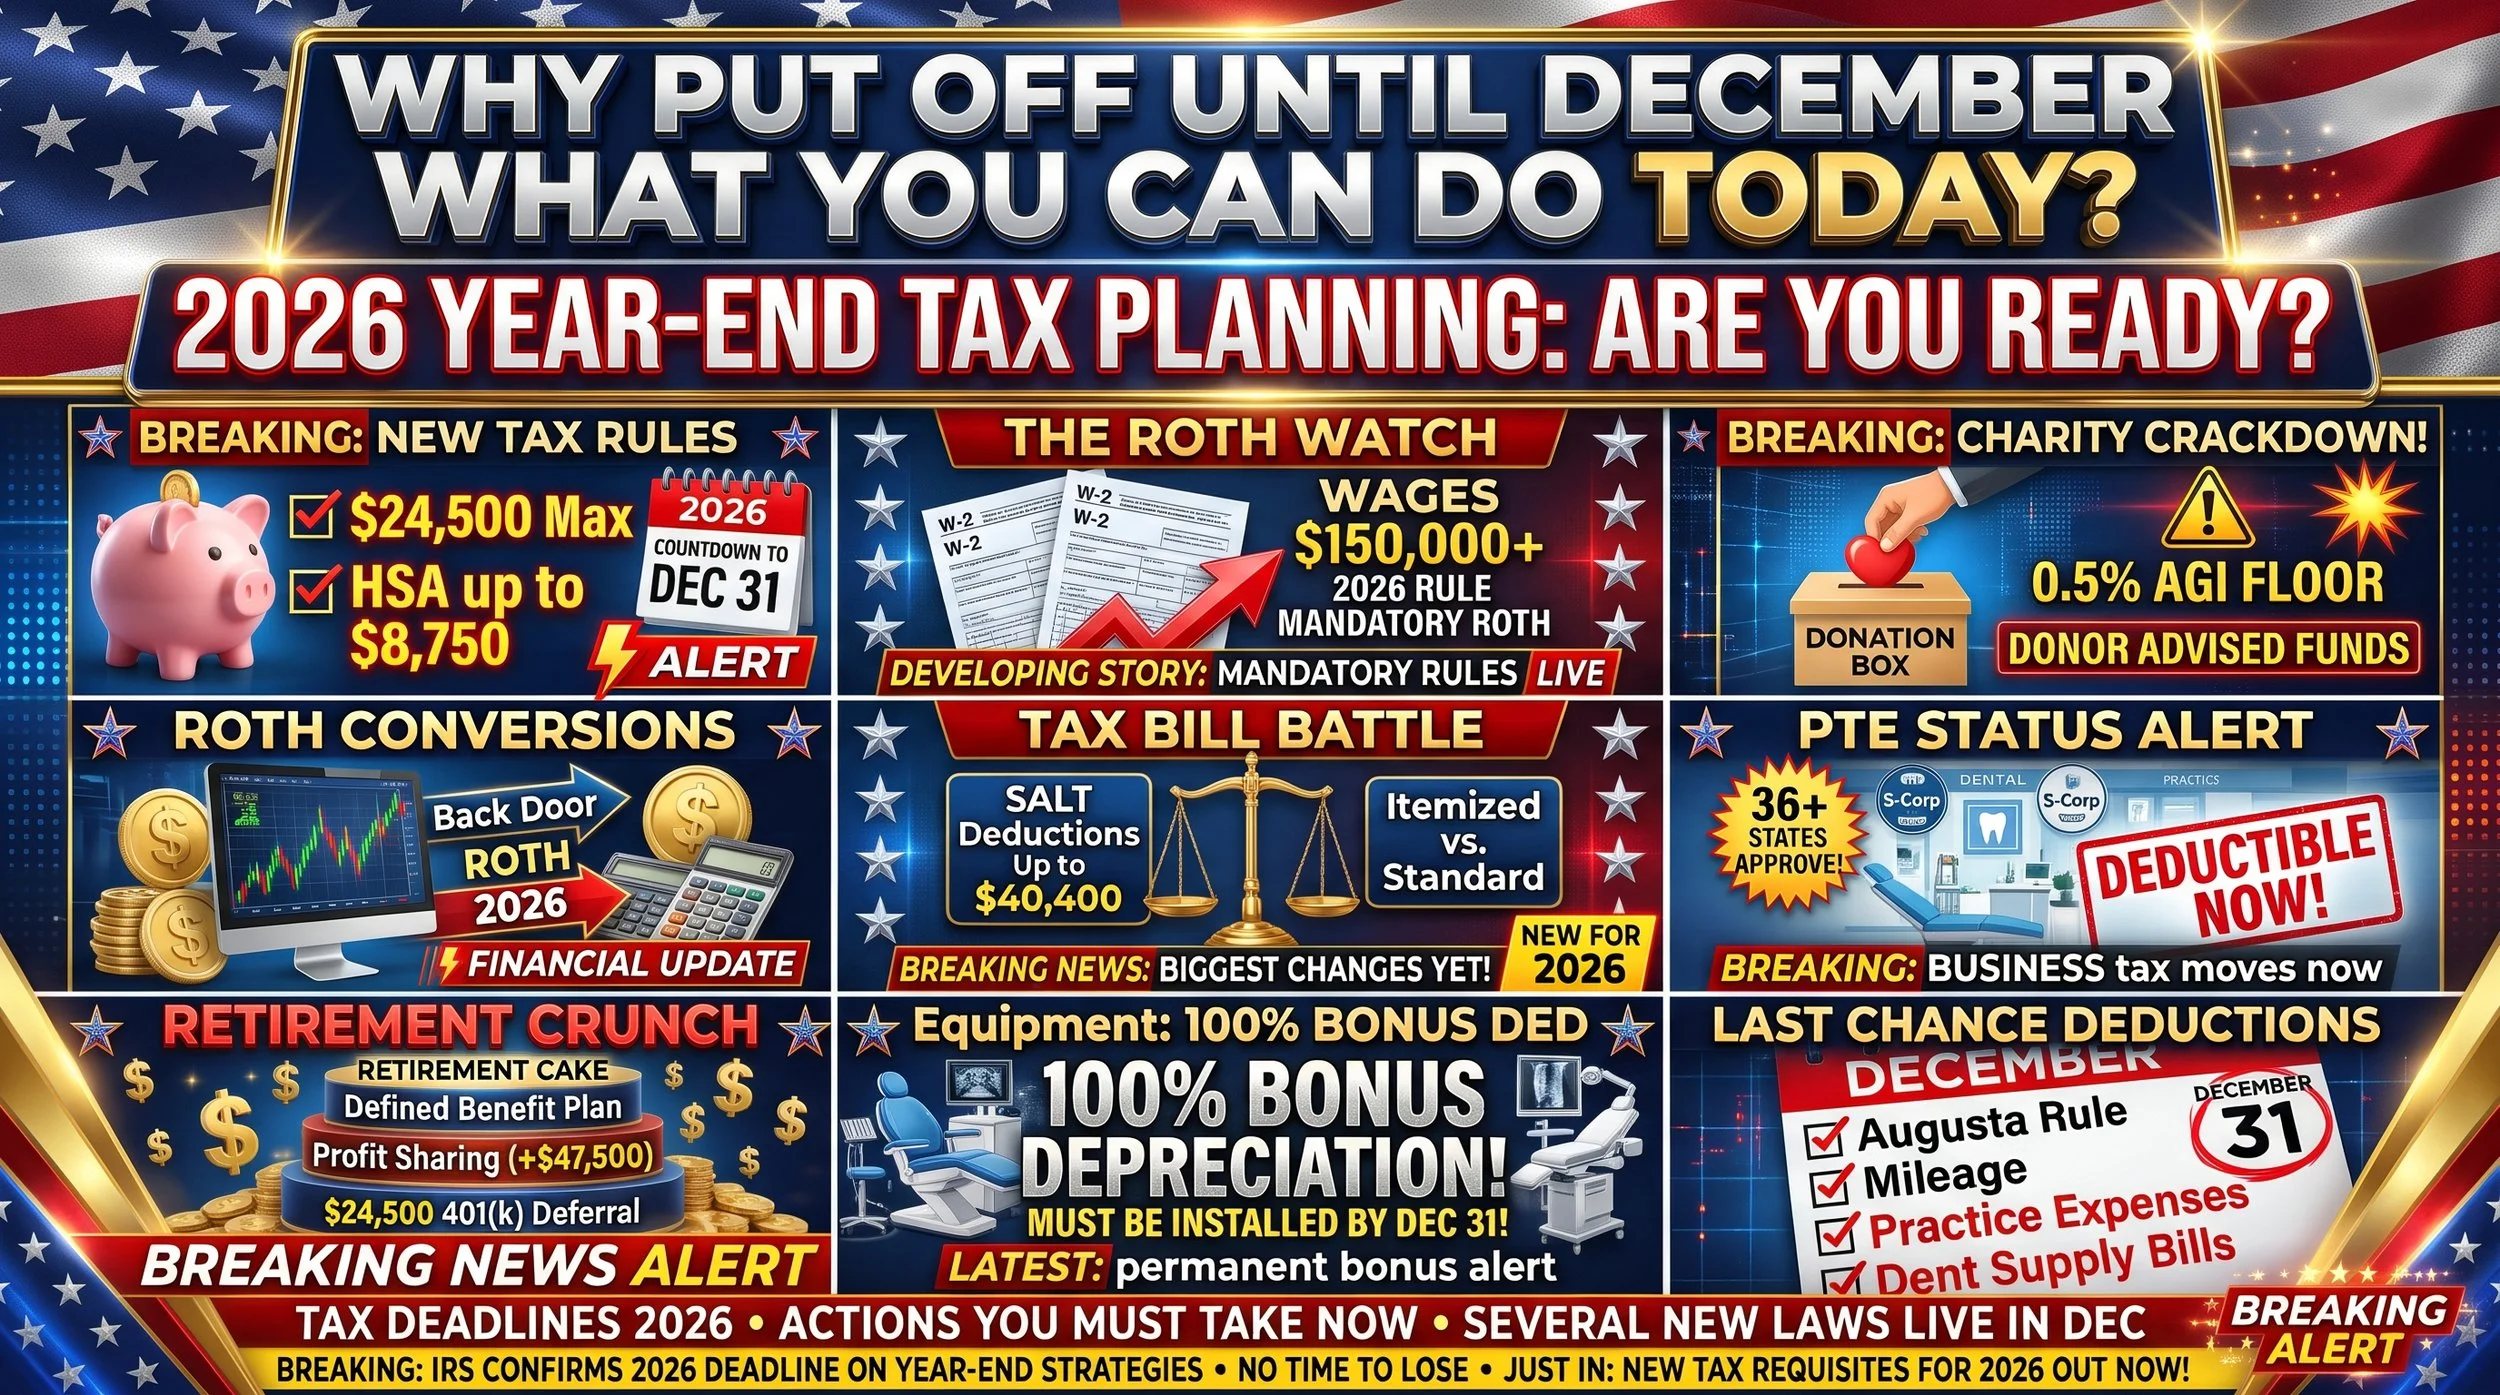
Why Put Off Until December What You Can Do Today?
Congress did not hand us a new tax bill in 2026, but that does not mean nothing changed. Several provisions of H.R. 1 (otherwise known as the “One Big Beautiful Bill”) were written to start in 2026, including:
New limits on charitable deductions
Haircut on itemized deductions for top-bracket taxpayers
The ROTH catch-up rule for higher earners
Expanded SALT deduction and its income phase-outs
Return of the stricter AMT (Alternative Minimum Tax) limits
With these compounding limits and phase-outs, the back-of-the-envelope math that used to work for tax planning no longer produces an accurate estimate. A simple $5,000 increase in interest income can bump you into a higher tax bracket and phase you out of a $10,000 tax credit.
As we enter the final months of 2026, it’s time to start making tax-saving moves now so you can enjoy your holidays in December. Remember that once the calendar turns to 2027, your options for reducing your 2026 tax bill shrink to a short list (primarily HSA and certain retirement contributions).
Review the list below to see if which steps you can take now.
PERSONAL TAX STRATEGIES
Maximize your 401(k) deferral
Make sure you are on track to max out your 401(k) contributions by year end. The 2026 base contribution limit is $24,500 with an additional $8,000 catch-up contribution if you are age 50 or older. If you turn 60, 61, 62 or 63 this year, your special SECURE 20 higher catch-up is $11,250 instead.
You should consider whether contributions to a Roth 401(k) would be more beneficial. A Roth contribution will not lower your current tax bill and may leave it higher. But the contributions and earnings growth are distributed tax-free in retirement making the Roth strategy advantageous when you are younger and in a lower tax bracket today than you expect to be in the future.
Additionally, be aware that starting in 2026, any employee age 50 or older who is earning more than $150,000 in wages may only make the $8,000 in catch-up contributions with after-tax dollars into a ROTH. If you are a dentist over 50, confirm your 401k plan has a ROTH option and that payroll is coding your catch-up correctly before the last paycheck of the year.
Health Savings Account
Make sure you are on track to maximize your HSA contributions by year end. The 2025 maximum contribution is $4,400 for individual plans and $8,750 for family plans. If you are 55 or older, you can contribute an additional $1,000 catch-up contribution.Monitor your Non-Retirement Investment Portfolio
Monitor your taxable portfolio (not retirement accounts) and harvest tax losses to offset capital gains if it makes sense when considering your overall investment strategy. If you are planning a large sale of appreciated stock, consider splitting it between December and January to spread the gain over two tax years.
Use Back Door ROTH
While you technically have until 4/15/2027 to fund your back door ROTH for 2026, we advise that you complete the process before the end of the year to avoid any timing or reporting issues. Remember that to get the most benefit, your IRA should have a zero balance before your 2026 contribution and the contributions and rollover should happen on the same day.
Consider a ROTH conversion
Since the HR 1 tax law extended the lower rates permanently (which just means until Congress changes them again), the next few years may be ideal to convert some of your traditional retirement accounts over to ROTHs in order to reap the benefits of tax-free withdrawals in retirement. Generally, you will want to convert just enough to fill the remainder of your current tax bracket.
As an example, you are married with 2026 taxable income of $350,000 and in the 24% tax bracket, which ranges from $211,401 to $403,550. You could convert $53,550 without being pushed up into the 32% bracket and paying higher federal income taxes. Keep in mind that a conversion raises your AGI (see below), so run the numbers to ensure you don’t lose any credits before you pull the trigger.
Plan for Charitable Contributions
The ugly little rules around charitable deductions that we previewed last year are now in effect. If you itemize, the first 0.5% of your adjusted gross income in donations is no longer deductible. With $400,000 of income, that means your first $2,000 of giving gets you nothing, whether you donate $3,000 or $30,000. On top of that, taxpayers in the top 37% bracket now get only 35 cents of benefit per dollar of itemized deductions.Because the 0.5% floor applies every year, bunching several years of gifts into one year with a Donor Advised Fund still makes sense. You clear the floor once, take a large itemized deduction in that year and use the standard deduction in the others.
There is some good news if you take the standard deduction. You can now deduct up to $2,000 of cash donations if married filing jointly ($1,000 if single). Gifts of property and gifts to Donor Advised Funds do not count.
If you are 70½ or older, qualified charitable distributions (QCDs) straight from your IRA were not touched by the new rules and are often still the most tax-efficient way to give.
Run the Standard vs. Itemized Numbers
The 2026 standard deduction is $32,200 for married couples and $16,100 for singles. The expanded deduction for state and local taxes (SALT) pushed many of our clients back into itemizing. For 2026 the SALT deduction is up to $40,400, but it starts shrinking once income passes $505,000 and drops back to $10,000 at roughly $606,000.If you are close to the line, consider alternating between the standard deduction and itemizing, and bunch your deductions into the itemizing years. Charitable gifts are the easiest to bunch (see above).
Keep an Eye on your AGI
Adjusted gross income is the number Congress uses to phase out more than a dozen tax breaks, including the SALT deduction above, and to trigger extras like the 3.8% net investment income tax and higher Medicare premiums. Itemized deductions do not reduce AGI. What does reduce AGI:pre-tax 401(k) and HSA contributions,
deductible practice expenses
realized capital losses
If you are near an AGI threshold, a few thousand dollars of AGI can matter more than you would expect.
Minimize paying IRS Interest
The IRS is still charging 7% on underpaid estimates. Verify that you have paid your required estimated payments, which are generally 110% of your prior year tax (100% if your prior year AGI was $150,000 or less) or 90% of this year’s tax. If you find yourself short, you can make a fourth quarter estimate due on 1/15/2027, but additional payroll withholding by 12/31/2026 is usually the better fix. Withholding is treated as if it were paid evenly throughout the year, so it can erase a penalty from earlier quarters where a late estimate cannot.
Know the New Gambling Rule
If you had a good (or bad) weekend in Las Vegas, note that starting in 2026 you can deduct only 90% of your gambling losses, and only if you itemize. The deduction still cannot exceed your winnings, so it is now possible to owe tax in a year where you broke even.
TAX PLANNING STRATEGIES FOR YOUR PRACTICE
Check on the PTE status in your state
Over 36 states now allow owners of PTEs (pass-through entities) like S-corps to pay state tax at the practice level. This rule is a workaround to avoid the cap on state tax deductibility on the personal return and can significantly reduce your total tax bill. Even with the larger $40,400 SALT cap, the PTE election is valuable, especially if your income is above $505,000 where the personal cap starts shrinking back to $10,000. To be deductible, the payment must be made before the end of 2026.Consider adding a Profit Sharing component to your 401k plan
Have you maximized your 401k deferrals (see above) but are looking for additional practice deductions and sitting on extra cash? Ensure that your 401k plan has a profit sharing option so you can potentially put another $47,500 into your retirement funds and get a tax deduction for it.
Look into a Defined Benefit Plan
If your debt is paid off and the practice cash flow is consistently high, it is probably time to set up a Defined Benefit Plan (also known as a cash balance plan) as the final step in building your retirement cake. It is a great tax tool as well since your contribution, which can reach well into six figures (the 2026 annual benefit limit is $290.000), is considered a deductible practice cost.
Decide on treatment for Research & Development Credits
For those who qualify (the window is small and the study costs are expensive), domestic research costs are once again deductible right away rather than capitalized. If you had R&D costs capitalized in 2022-2024, the window for small businesses to amend those returns generally closed in July 2026. If you instead chose to deduct the leftover costs across 2025 and 2026, make sure the second half lands on your 2026 return.
Pay yourself and any vendors before year-end
Once the clock strikes midnight on December 31st, all payments (except for a few odd exceptions like profit sharing) are considered 2027 expenses. Make sure that you have paid yourself for any Augusta Rule rental costs and reimbursed yourself for business mileage before year end. You can also pay the dental supply bill due in early January during the last week of December if you are looking for additional deductions.
Purchase NEEDED equipment
This is always the equipment salesman’s favorite way for you to reduce your tax bill. With 100% bonus depreciation now permanent, you can deduct the full cost of the equipment in 2026 rather than spreading it across the next five years. If you:
have some equipment that you are going to purchase in the next 12 months
are flush with cash or can get a 12 month 0% financing deal
can get a great deal with year-end pricing,
…it may be a great time to purchase that equipment and reduce your tax bill at the same time. Just remember the equipment has to be installed and in use by December 31st, not simply ordered.
Since each practice and each tax situation is different, please schedule a consultation with JNG Advisors today to see what tax planning strategies you can implement for you.